South Korea’s soaring housing costs and heavy household debt are changing something once considered a basic milestone of adulthood. More people in their 30s are remaining single, some couples are skipping wedding ceremonies altogether, and others are delaying the legal registration of their marriages because getting married can complicate access to housing programs.
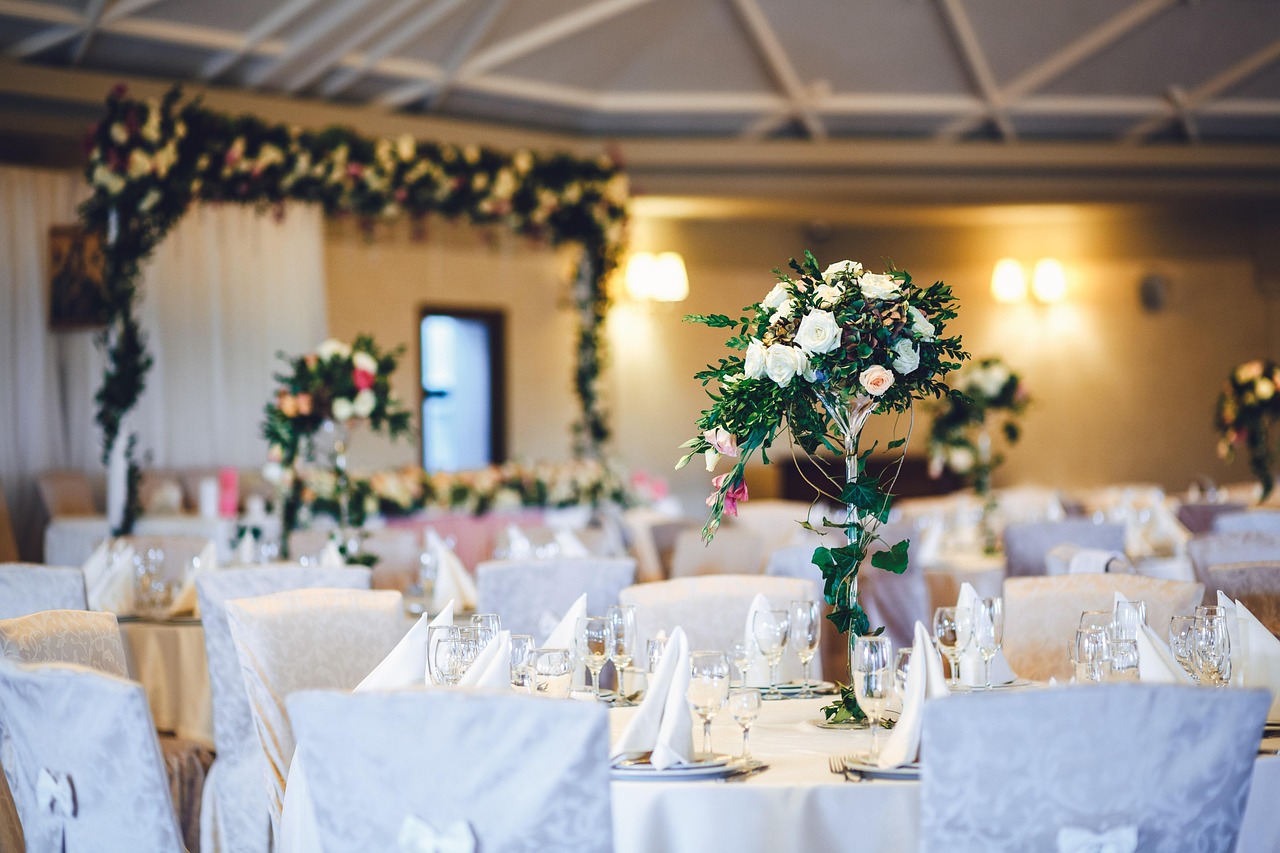
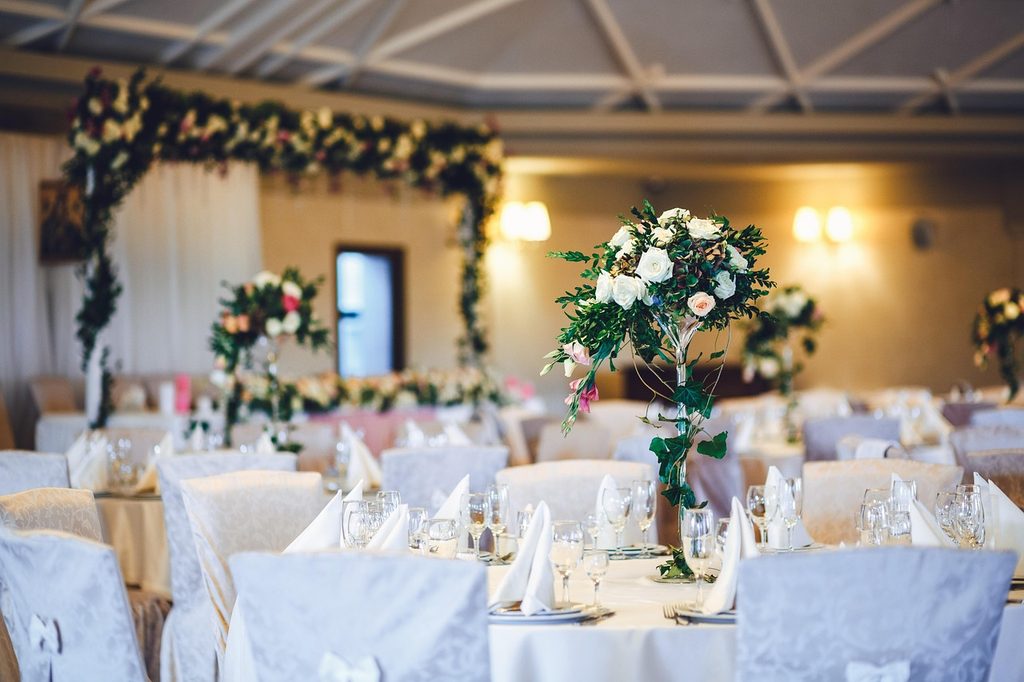
The consequences are beginning to show up in the broader economy. Wedding venues are closing as demand weakens, while younger couples are reconsidering whether money once spent on ceremonies, photography, dresses and large receptions should instead go toward a home, investments or debt payments. The unmarried rate among South Koreans in their 30s has reached 54.7%, while single person households account for 36.6% of all households, according to figures cited by former television personality and YouTuber Pyo Young ho.
The shift matters well beyond South Korea’s wedding business because it shows how high housing costs and borrowing expenses can reshape consumer behavior and even family formation in an advanced economy. When buying a home requires large loans and monthly interest payments consume more income, marriage itself can become part of a household’s financial planning rather than simply a personal or cultural decision.
That calculation is changing the wedding ceremony first. Some couples are choosing what has become known as a no wedding approach, skipping formal ceremonies as the combined cost of photography, dresses, makeup, invitation gatherings and reception meals rises. Pyo cited survey data showing that 27% of unmarried men and women said they would forgo a wedding if the cost became too burdensome.
For some couples, the decision goes further. They hold a ceremony but delay legally registering the marriage. In South Korea, income limits can affect eligibility for special apartment allocation programs and other housing benefits aimed at newlyweds. Once two incomes are combined after marriage, some couples can find themselves above the qualifying threshold or with fewer opportunities in the country’s competitive housing subscription system.
The government has relaxed some of those rules, but Pyo said couples continue to postpone legal registration because they believe the financial disadvantages remain significant. The result is an unusual gap between social marriage and legal marriage, created in part by the economics of housing.
Debt adds another layer of pressure. The median outstanding loan balance among first time newlywed couples has risen to about $132,000, more than 130% above its 2016 level. About 24% hold more than $220,000 in loans, while the median balance among newlyweds who own homes is approaching $200,000.
Those debts have become more painful as interest rates have remained high. Couples who borrowed heavily when financing was cheaper can now face much larger monthly payments, leaving less room for discretionary spending even after they have managed to buy a home.
That is why the decline of South Korea’s wedding halls is more than a story about changing tastes. It is a visible sign of a broader reallocation of household money.
Spending that once went toward ceremonies and traditional milestones is increasingly being weighed against housing, debt repayment and long term financial security.
The decline of South Korea’s wedding halls is therefore more than a story about changing tastes. It is evidence that housing costs and debt are beginning to redirect household spending away from traditional life events and toward homes, financial assets and debt repayment. That shift threatens businesses built around large weddings while showing how prolonged housing pressure can reshape consumer markets in one of Asia’s wealthier economies.