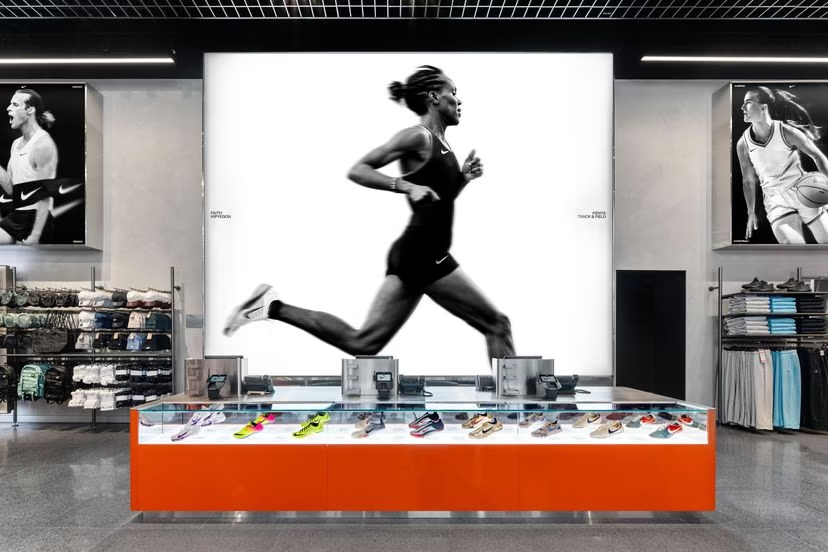
Nike built the world’s largest sportswear business by dominating both athletic performance and everyday sneakers. That scale is still enormous, but it is no longer translating into the kind of growth investors once expected. The company is struggling to revive sales globally while specialist running brands such as Hoka and On capture consumers who increasingly want cushioned shoes for training, commuting and casual wear.
South Korea is becoming one of the clearest examples of that pressure. Nike Korea’s revenue fell for a third consecutive year in fiscal 2026, dropping 5.2% to $1.31 billion from $1.38 billion a year earlier, according to filings with South Korea’s Financial Supervisory Service. Revenue has now fallen about $160 million, or 10.8%, from its fiscal 2023 peak of $1.48 billion.
The decline matters well beyond Korea because it mirrors a broader problem confronting one of America’s most recognizable consumer companies. Nike is not disappearing, and its racing shoes such as the Alphafly and Vaporfly remain prominent among serious runners. What has changed is the market around them. Hoka, owned by U.S. footwear company Deckers Brands, and Swiss running brand On have expanded rapidly in daily training and lifestyle footwear, while Asics and New Balance have given consumers even more alternatives.
Deckers reported fiscal 2026 revenue of $5.4 billion, up 10%, while Hoka sales climbed 15.9% to $2.5 billion. On reported about $2 billion in first half revenue this year, up 14%, or 24% excluding currency effects.
That contrast helps explain why Nike’s troubles cannot be reduced to weak consumer spending in a single market. Korea has experienced a running boom, yet Nike’s local revenue has continued to shrink while running focused competitors have expanded. The problem is increasingly about where runners are spending their money, not whether they are spending at all.
Nike Korea’s latest results also illustrate another question facing investors. The business became substantially more profitable even as sales declined.
Operating profit more than doubled to $60 million from $27 million, while its operating margin rose to 4.6% from 2%. Net income increased to $59 million from $22 million. The improvement came largely from lower costs rather than stronger demand.
Cost of goods sold fell 9.3% to about $1 billion, considerably faster than the 5.2% drop in revenue. Gross profit increased 12.4% to roughly $297 million, while gross margin climbed to 22.6% from 19.1%. The cost figure also included a negative transfer pricing adjustment of about $34 million.
The numbers show that Nike can improve profitability while shrinking, but that is different from restoring growth. After three years of falling Korean revenue, the larger test is whether the company can bring consumers back without giving up the margin improvements created through tighter cost control.
Nike is also trying to repair a distribution strategy that helped reshape its relationship with shoppers.
For years, the company pushed Nike Direct, selling more products through its own stores, website and apps while reducing its dependence on outside retailers. The strategy promised higher margins and more control over customer data.
It also gave rival brands an opening. Multibrand sporting goods stores allow consumers to compare shoes side by side, and Hoka, On and other challengers used those retail shelves to put their products directly in front of shoppers while Nike focused more heavily on its own channels.
Nike is now rebuilding its wholesale business. Wholesale revenue rose 6% to $27 billion in fiscal 2026, while Nike Direct revenue fell 6% to $17 billion. Nike brand digital sales declined 12%, and sales from company operated stores fell 4%.
The company has said it will reinvest in wholesale distribution, increase its visibility in physical stores and accelerate new product launches while reducing supplies of some older footwear.
The pressure extends across Nike’s global business. Fiscal 2026 revenue was $46.4 billion, essentially flat from a year earlier and down 2% excluding currency movements.
Compared with roughly $51 billion in fiscal 2024, revenue has fallen 9.7% in two years.
Net income declined to $3.1 billion, down 3.4% from the previous year and 45.5% below fiscal 2024 levels.
Regional results also show that the weakness is uneven rather than universal. North American revenue increased 4.8%, while Greater China revenue fell 11% to $5.8 billion.
Revenue in Asia Pacific and Latin America, which includes South Korea, was roughly unchanged at $6.2 billion and declined 1% excluding currency effects. Nike said weaker sales in South Korea, Japan and Southeast Asia weighed on the region.
Investors have already repriced the company sharply. Nike shares, which reached $177 in November 2021, closed at $36 on Sept. 11, a decline of more than 79%.
S&P Dow Jones Indices is also set to remove Nike from the S&P 100 before the U.S. market opens Sept. 21, ending a run in the index that began in December 2008. Nike will remain in the broader S&P 500.
Nike remains a giant in sportswear. The question is no longer whether it has the scale to compete. It is whether that scale can again produce growth while runners are increasingly willing to look beyond the swoosh.
Korea offers an early answer to that question. Consumers are still buying running shoes, but more of them are choosing someone else’s.